What Lenders Look for in a Draw-Ready WIP Schedule
If you've ever waited on a draw release that felt like it took forever, the hold-up probably wasn't the lender being difficult — it was your WIP schedule not telling the story they needed to see. A work-in-progress schedule isn't just an internal report; it's the document a lender uses to decide whether to release the next round of capital on your project. If it doesn't match your AIA billing, your job-cost detail, or your contract value, the draw stalls.
What a draw-ready WIP schedule actually includes
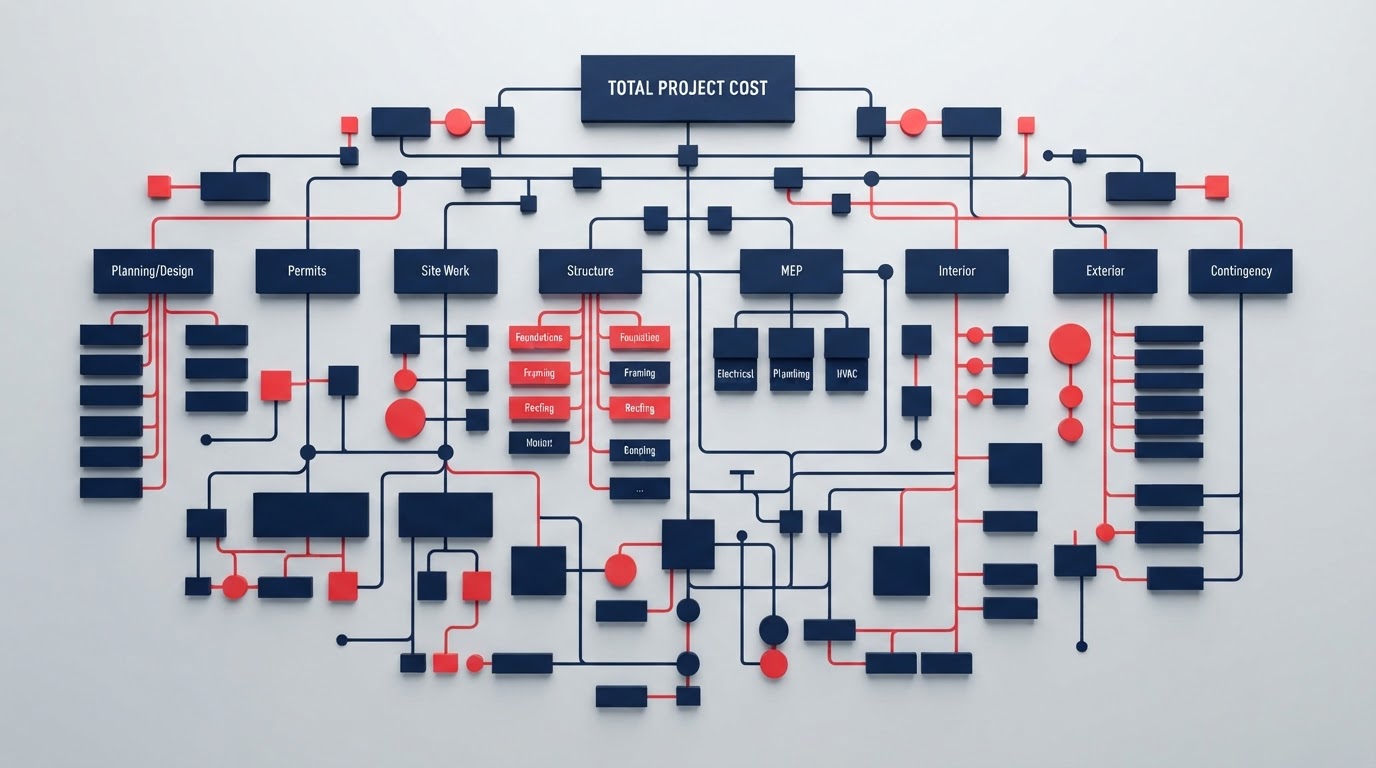
A clean WIP schedule shows three things clearly: the total contract value, the costs incurred to date, and the costs committed but not yet billed. Lenders want to see that the percentage of work completed lines up with the percentage of costs incurred. If you're 80% through the project but only 60% through the budget, that's a red flag — and it's the kind of thing that stops a draw cold.
- Contract value and any approved change orders, with documentation
- Costs incurred to date, broken down by job-cost category
- Costs committed but not yet invoiced (POs, subs, materials)
- Percentage complete — calculated consistently every period
- Remaining contract value and remaining costs to complete
The consistency problem
The most common problem isn't a missing number — it's an inconsistent method. If your percentage complete is calculated differently from month to month, or your job-cost categories don't match what you bill on the AIA, the lender can't reconcile the package. They don't have time to dig through your books and figure out why the numbers don't match. They just hold the draw until they do.
This is why HLD sets up your books around job costing from day one — so the WIP schedule you hand to a lender is the same schedule you run your business on. No translation, no catch-up cleanup, no scrambling before a draw request. When the books and the lender package come from the same desk, the numbers match the first time.
Bottom line
A draw-ready WIP schedule isn't about adding more detail — it's about consistent, clean, lender-readable structure from the start. If you're rebuilding your WIP every time a draw comes up, your books aren't doing the job they could be.
Want this kind of analysis on your deal? Book a 30-minute call — we'll walk through the numbers with you.